
Mid-Peninsula Market Pulse — Week of November 6–12, 2026
Here's this week's San Mateo County housing market read across the ten Mid-Peninsula cities I track: Belmont, Burlingame, Foster City, Hillsborough, Menlo Park, Palo Alto, Redwood City, Redwood Shores, San Carlos, and San Mateo.
The short version:
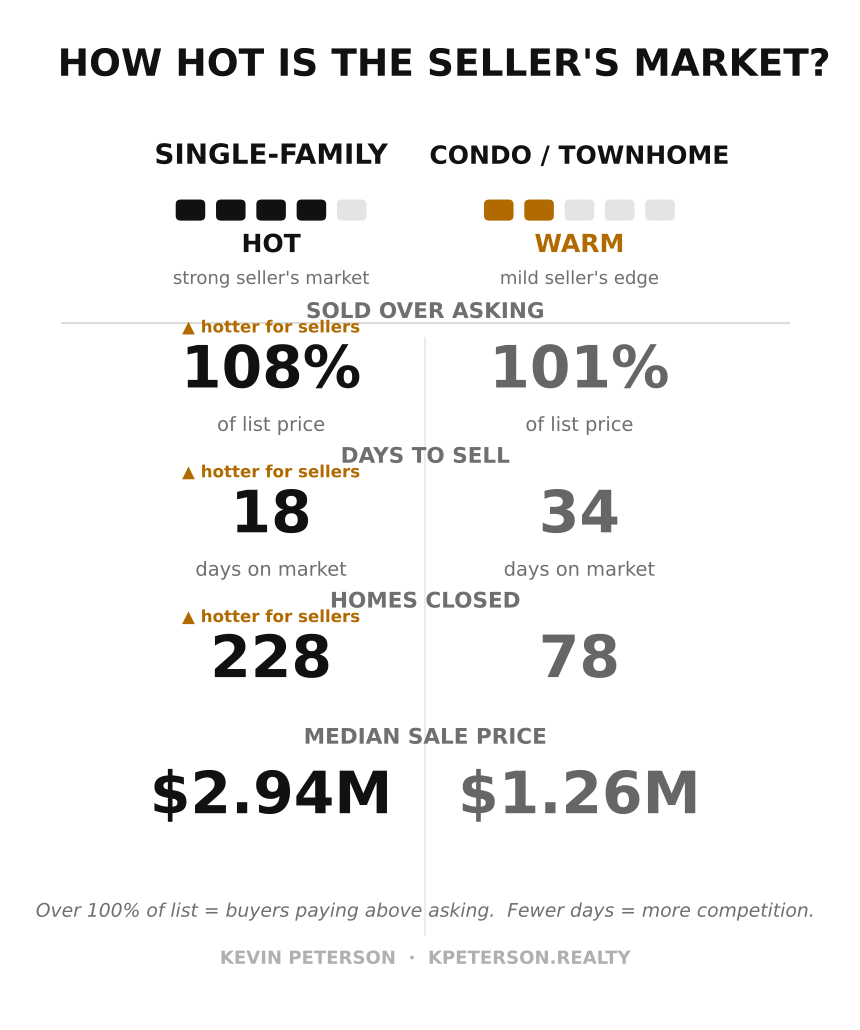
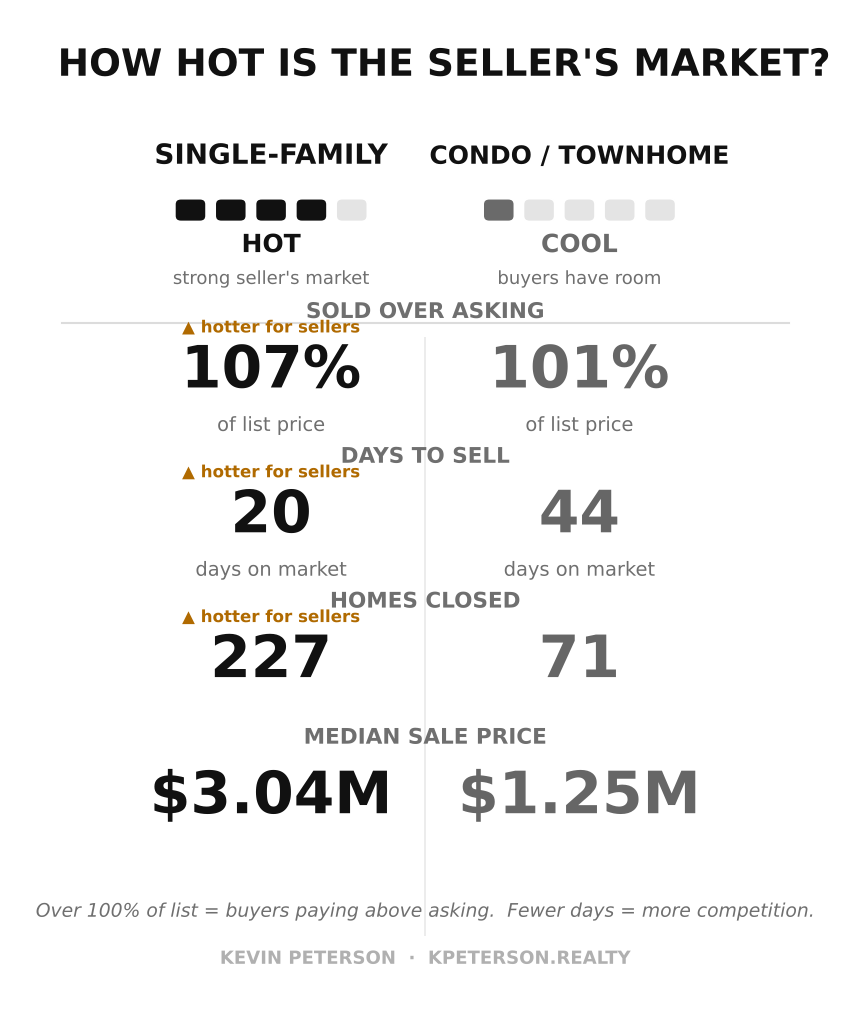
Sellers: Single-family homes sold at 108.2% of list in about 17 days (a median of 11), and every price band closed over asking.
Buyers: Condos and townhomes sold at 100.1% of list with a median of 20 days on market. This week's 9 condo closings came in just under asking at 99.3% of list, with a median of 27 days.
Rates: The 30-year fixed averaged 7.11% this week, down from 7.18% a week ago but up from 6.24% a year ago (Freddie Mac, November 12, 2026).
Inventory: Single-family active listings are 249, 7% below a year ago, and they've held about even over the past four weeks while the same stretch brought 14–15% drops in each of the past two falls, because fewer homes are going under contract (pending is 18% below last year).
The data: 307 closed sales in ten San Mateo County and Santa Clara County Peninsula cities, October 13 – November 12, from MLS Listings.

Local Market Activity (October 13 – November 12)
The Mid-Peninsula closed 307 homes in the last 30 days — 38 just this week. The typical home sold for $2.29M and went for 106% of asking, so sellers are still getting a premium over list. (This week's count is light: Veterans Day fell on Wednesday, and today's closings are still being reported.)
Palo Alto (44), Redwood City (39) and San Mateo (34) led single-family volume, while Hillsborough had the highest single-family median at $6.15M. San Mateo (19) and Palo Alto (15) led condos and townhomes, and San Carlos posted the highest condo median at $1.83M.

Single-Family by Price Point
Here's how the 224 single-family sales in the last 30 days broke down by price point:
Under $2M: 52 sold at 102.0% of list in about 19 days.
$2–3M: 75 sold at 110.4% of list in about 18 days — the busiest tier and the hottest by sale-to-list.
$3–4.5M: 61 sold at 110.0% of list in about 14 days — the fastest-moving tier.
$4.5M+: 36 sold at 109.6% of list in about 18 days.
Over-asking isn't just an entry-level story here — it runs all the way up the price ladder, and the under-$2M tier is actually the closest to list.

This Week vs. the 30-Day Pace
Single-family homes are holding a steady pace: 224 sold over the last 30 days in about 17 days at 108.2% of list, versus 83 condos and townhomes at about 31 days and 100.1% of list. This week's 29 single-family closings came in at 106.3% of list. Their 26-day average on market is pulled up by one San Mateo home that sat 212 days; the median was 12 days, close to the 30-day median of 11. This week's single-family sales also skewed toward lower price points, with a median of $2.30M versus $2.75M for the 30-day window.
Condos and townhomes: 9 closed this week at 99.3% of list. The 30-day average of 31 days is inflated by a few long-sitting units (the longest, in Redwood City, took 174 days); the median is a more typical 20 days, and this week's condo median was 27 days.

Inventory: Active, Pending and Sold (3-Year View)
Is supply building or shrinking, and how fast? This compares the same ten cities this week with the same week in 2025 and 2024. Active means on the market and available, pending means under contract (contingent plus pending), and sold is a 4-week average of weekly closings.
Single-family: 249 homes are active, 7% fewer than the 269 a year ago and about even with the 247 in 2024. Over the past four weeks single-family inventory barely moved (253 to 249, about even), while the same four weeks brought drops of 15% in 2025 and 14% in 2024. So the gap to last year is narrowing fast: four weeks ago inventory was 20% below last year; now it's 7% below.
Why? Fewer homes are going under contract, so fewer listings leave the active pool. Pending single-family listings are at 150, down 8% in four weeks (versus a 4% dip over the same stretch in 2025 and a 21% drop in 2024) and 18% below last year's 183, the lowest for this time of year in three years. Closings have averaged about 43 a week over the last four weeks, versus 56 a year ago and 62 in 2024 (this week's count is light because of the Veterans Day holiday). Put together, that's 5.8 weeks of supply, up from 4.8 a year ago and 4.0 in 2024. That's still a tight market, but with a little more breathing room than the past two falls.
Condos and townhomes: 195 active, 13% fewer than 223 a year ago and 4% more than the 187 in 2024. Condo inventory fell 8% over four weeks, slower than last year's 14% drop and a bit faster than 2024's 6%. Pending sits at 57, down 11% in four weeks and 23% below last year; closings averaged about 15 a week (versus 18 and 16), for roughly 13.0 weeks of supply (12.6 a year ago, 11.7 in 2024). That's more than twice the single-family cushion, which gives condo buyers more room to negotiate.
Bottom line: Single-family inventory isn't building in absolute terms (it's about where it was a month ago), but the usual fall drop-off has nearly stopped because contracts and closings are running below the past two years. That tilts things slightly toward buyers compared with recent falls, while sellers still hold the edge on price. Next week, watch whether pending listings stabilize now that rates have eased to 7.11%. Note: prior-year counts are rebuilt from MLS listing and status dates and may run slightly low.

The Move Math
Here's what today's numbers mean for a move, using current medians and this week's 7.11% 30-year rate. (Payments are principal + interest, 20% down; taxes and insurance are on top.)
Trading up — condo to single-family:
Median condo ($1.20M): 20% down is $240,000. Financing the other 80% at 7.11% means P&I of about $6,460/month, plus HOA. Many condo buyers today are investors, and many pay all cash.
Median single-family ($2.75M): 20% down is about $550,000, and P&I runs about $14,800/month. Buyers at this level often put 40–50% down or pay all cash because of rates and opportunity cost.
That's a monthly gap of roughly $8,300 before taxes and insurance.
Downsizing at 55+ — don't forget Prop 19.
If you're 55 or older, Prop 19 lets you carry your existing low property-tax base to your next California home, up to three times, anywhere in the state (if the new home costs more, the difference is added). On a long-held home, that can mean keeping a tax bill tied to a $500–700K assessed value instead of today's price, often $20,000+ a year saved.
The Macro Corner.
Mortgage rates: The 30-year fixed averaged 7.11% (7.18% last week, 6.24% a year ago) and the 15-year 6.45% (6.57%, 5.49%), the fourth straight weekly decline and the lowest in seven weeks (Freddie Mac, November 12).
The Fed: Held at 3.75%–4.00% on October 28 in a 10–2 vote; Lisa Cook and Beth Hammack dissented in favor of a quarter-point hike. The next meeting is December 8–9, and after the October CPI, futures priced roughly a 90% chance of a quarter-point hike (CME FedWatch, November 10).
Inflation: October CPI rose 0.4% for the month (core +0.3%), above forecasts. The BLS published no year-over-year rate because October 2025 data was never collected during the shutdown; estimates put headline near 4%. Latest official annual figures: headline CPI 3.7% and core CPI 2.6% (September); core PCE 3.1% (September).
Wall Street: For the week ending November 6, the Dow fell 0.9%, the S&P 500 2.7% and the Nasdaq 3.4%, as investors reassessed AI spending after the midterm elections.
Bottom line: Rates have eased four weeks in a row, but hotter inflation and a likely December hike could push them back up.
Zooming out, this week's 7.11% is below October's 7.40% peak but still near the top of the three-year range: the high was 7.44% in November 2023 and the low 5.98% in February 2026, with a three-year average of 6.64%.

Bay Area Home Buyer and Seller FAQ
Is the San Mateo County housing market a seller's market right now?
Yes, for single-family homes. Over the last 30 days they sold at 108.2% of list in about 17 days, and every price band closed over asking. Condos and townhomes are closer to balanced at 100.1% of list with a median of 20 days on market.
What is the median home price on the Mid-Peninsula?
The combined median sale price across the ten cities was $2.29M over the last 30 days: $2.75M for single-family homes and $1.20M for condos and townhomes. Single-family city medians ranged from $2.00M in San Mateo to $6.15M in Hillsborough.
What are mortgage rates today, and what do they mean for a Bay Area move?
Freddie Mac's 30-year fixed average is 7.11% this week (November 12, 2026). With 20% down, principal and interest is about $6,460/month on the median condo and $14,800/month on the median single-family home, a gap of roughly $8,300/month before taxes and insurance.
Is it easier to buy a condo or townhome than a single-family home?
Generally, yes. Condos and townhomes sold at about 100% of list with a median of 20 days on market and about 13 weeks of supply, versus 108% of list, a median of 11 days and 5.8 weeks of supply for single-family homes. That gives condo buyers more room to negotiate.
How does Prop 19 help Bay Area homeowners 55 and older who want to downsize?
Prop 19 lets California homeowners 55 and older transfer their existing property-tax base to a replacement home anywhere in the state, up to three times. On a long-held home, that can save $20,000+ a year compared with being taxed on today's price. Check with a tax professional about your situation.
Which cities does this market report cover?
Belmont, Burlingame, Foster City, Hillsborough, Menlo Park, Palo Alto, Redwood City, Redwood Shores, San Carlos and San Mateo, using closed sales from MLS Listings. Prices are medians, which a few very high or low sales can't skew; days on market are averages unless noted as medians.
Want Your Personal Move Math?
Every move is different. Find out what your home is worth and run your own numbers: See what your home is worth →

Comments